One clear plan for your money in two countries.
Residence, treaties, your company, your estate: between the UK and your home country, every tax question turns on where you live and where your money works. Settle the UK side with Sebastian before you decide.
| Topic | tax questions between the UK and your home country |
| UK tax year | 6 April to 5 April |
| Residence | automatic from 183 days in the UK in the tax year |
| FIG regime | 4 years after at least 10 years outside the UK |
| Inheritance tax | overseas assets too, after 10 of the previous 20 years of UK residence |
| Consultation | one hour with Sebastian Sauerborn, £750 |
| As of | November 2026 |
When your life spans two countries
Move to the UK, run a company there or hold assets there, and two tax authorities start asking questions. Where are you resident? Which country may tax which income? And what does your home country expect when you leave? On the UK side, every answer starts with the tax year from 6 April to 5 April and with the days you spend in the country.
Spend 183 days or more in the UK in a tax year and you are resident automatically. With fewer days, the sufficient ties test can still make you resident, for instance through work or family in the UK. Once you are resident, the UK normally taxes all your income, wherever it arises. How the two countries then share the right to tax is set by the double tax treaty between the UK and your home country.
Which country has the final word
Nothing stops both countries from treating you as resident at the same time, typically in the year you move or when you keep a home in each. The treaty's tie-breaker then settles it, test by test, starting with the permanent home. If it makes you non-UK resident, you can usually claim relief from UK tax. If it makes you UK resident, the UK taxes your worldwide income and gains, and the other country gives way. The full sequence is in how UK tax treaties work.
Companies get a tie-breaker too: HMRC considers that every UK tax treaty has one for companies. Many still look to the place of effective management, where the key management and commercial decisions are in substance made. Others, including treaties changed by the multilateral convention, leave it to the two tax authorities to agree. Whether your home country also claims you or your company is set by its own law, and that is the half you want to know before you sign anything in the UK.
What you bring to the conversation
Each of these questions has a UK side and a home-country side.
What your consultation with Sebastian settles
You describe your situation, Sebastian sets out the UK side: which UK taxes apply, which deadlines are running, where your home country has a say and which decisions come before the first step.
The most common cases: the move with a share portfolio and a stake in a company, the UK limited company meant to be run from home, the house in London next to a life elsewhere in Europe, the estate that lands in two countries. Each one starts with the same three questions: where do you live, where does your money work, and what are you planning?
Who you plan it with
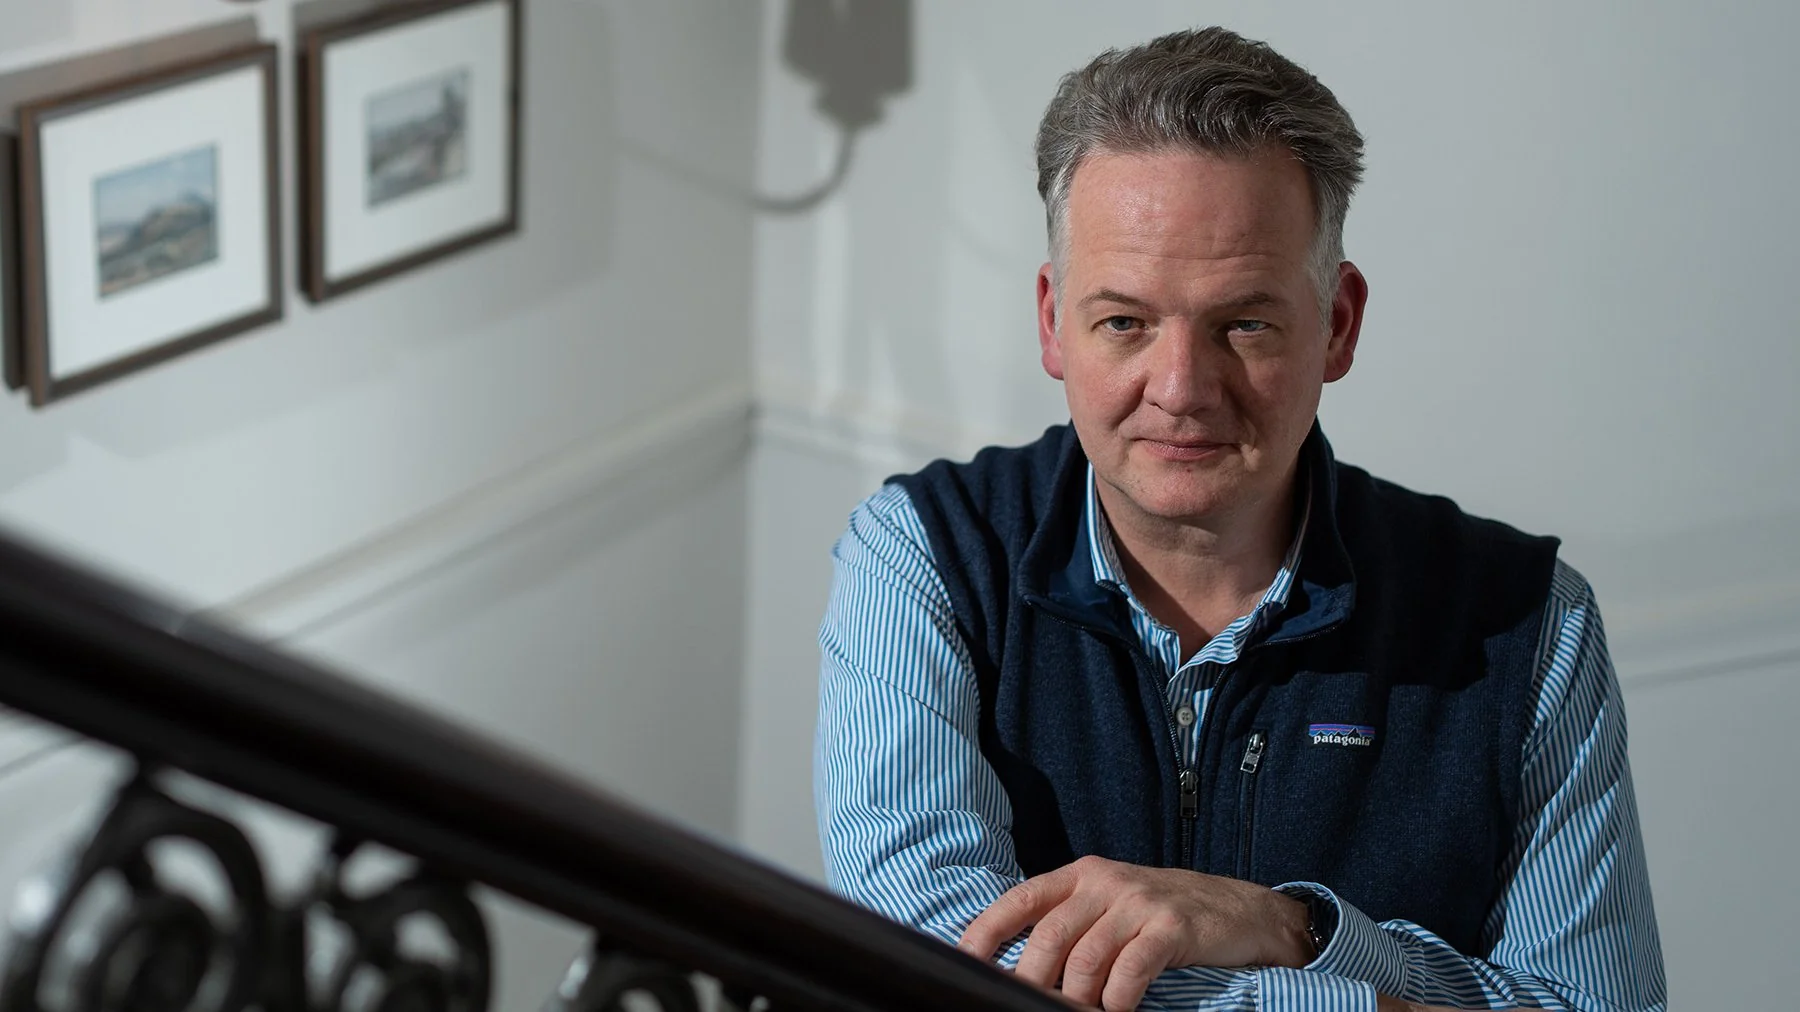
Sebastian Sauerborn founded St Matthew in London in 2006.
For twenty years I've answered UK tax questions for clients whose lives and businesses reach across a border. Most of those questions have an international side, and that side decides how much of your money you keep.
These days Sebastian runs St Matthew from Austin, Texas, as part of Perspektive Ausland.
Your questions on international tax
When do I become UK resident for tax?
Automatically, if you spend 183 days or more in the UK in a tax year. With fewer days, your ties to the UK decide, such as work or family there.
What does the FIG regime give me?
In your first 4 years as a UK resident after at least 10 years outside the UK, you pay no UK tax on eligible foreign income and gains if you claim. It replaced the remittance basis on 6 April 2025.
Can my assets outside the UK fall under UK inheritance tax?
Since 6 April 2025 that depends on long-term residence: if you were UK resident for 10 of the previous 20 years, your assets outside the UK may be subject to UK inheritance tax. After you leave, this can follow you for up to 10 tax years.
Where does my UK company pay tax if I run it from home?
Your home country may treat a company managed there as its own resident under its law. If both countries claim the company, the treaty's tie-breaker decides: in many UK treaties by the place of effective management, in others by agreement between the two tax authorities.
What does the consultation cost?
An hour with Sebastian costs £750.
What does your plan mean for your money in two countries?
Talk through your move, your company, your home or your estate directly with Sebastian, before you decide.